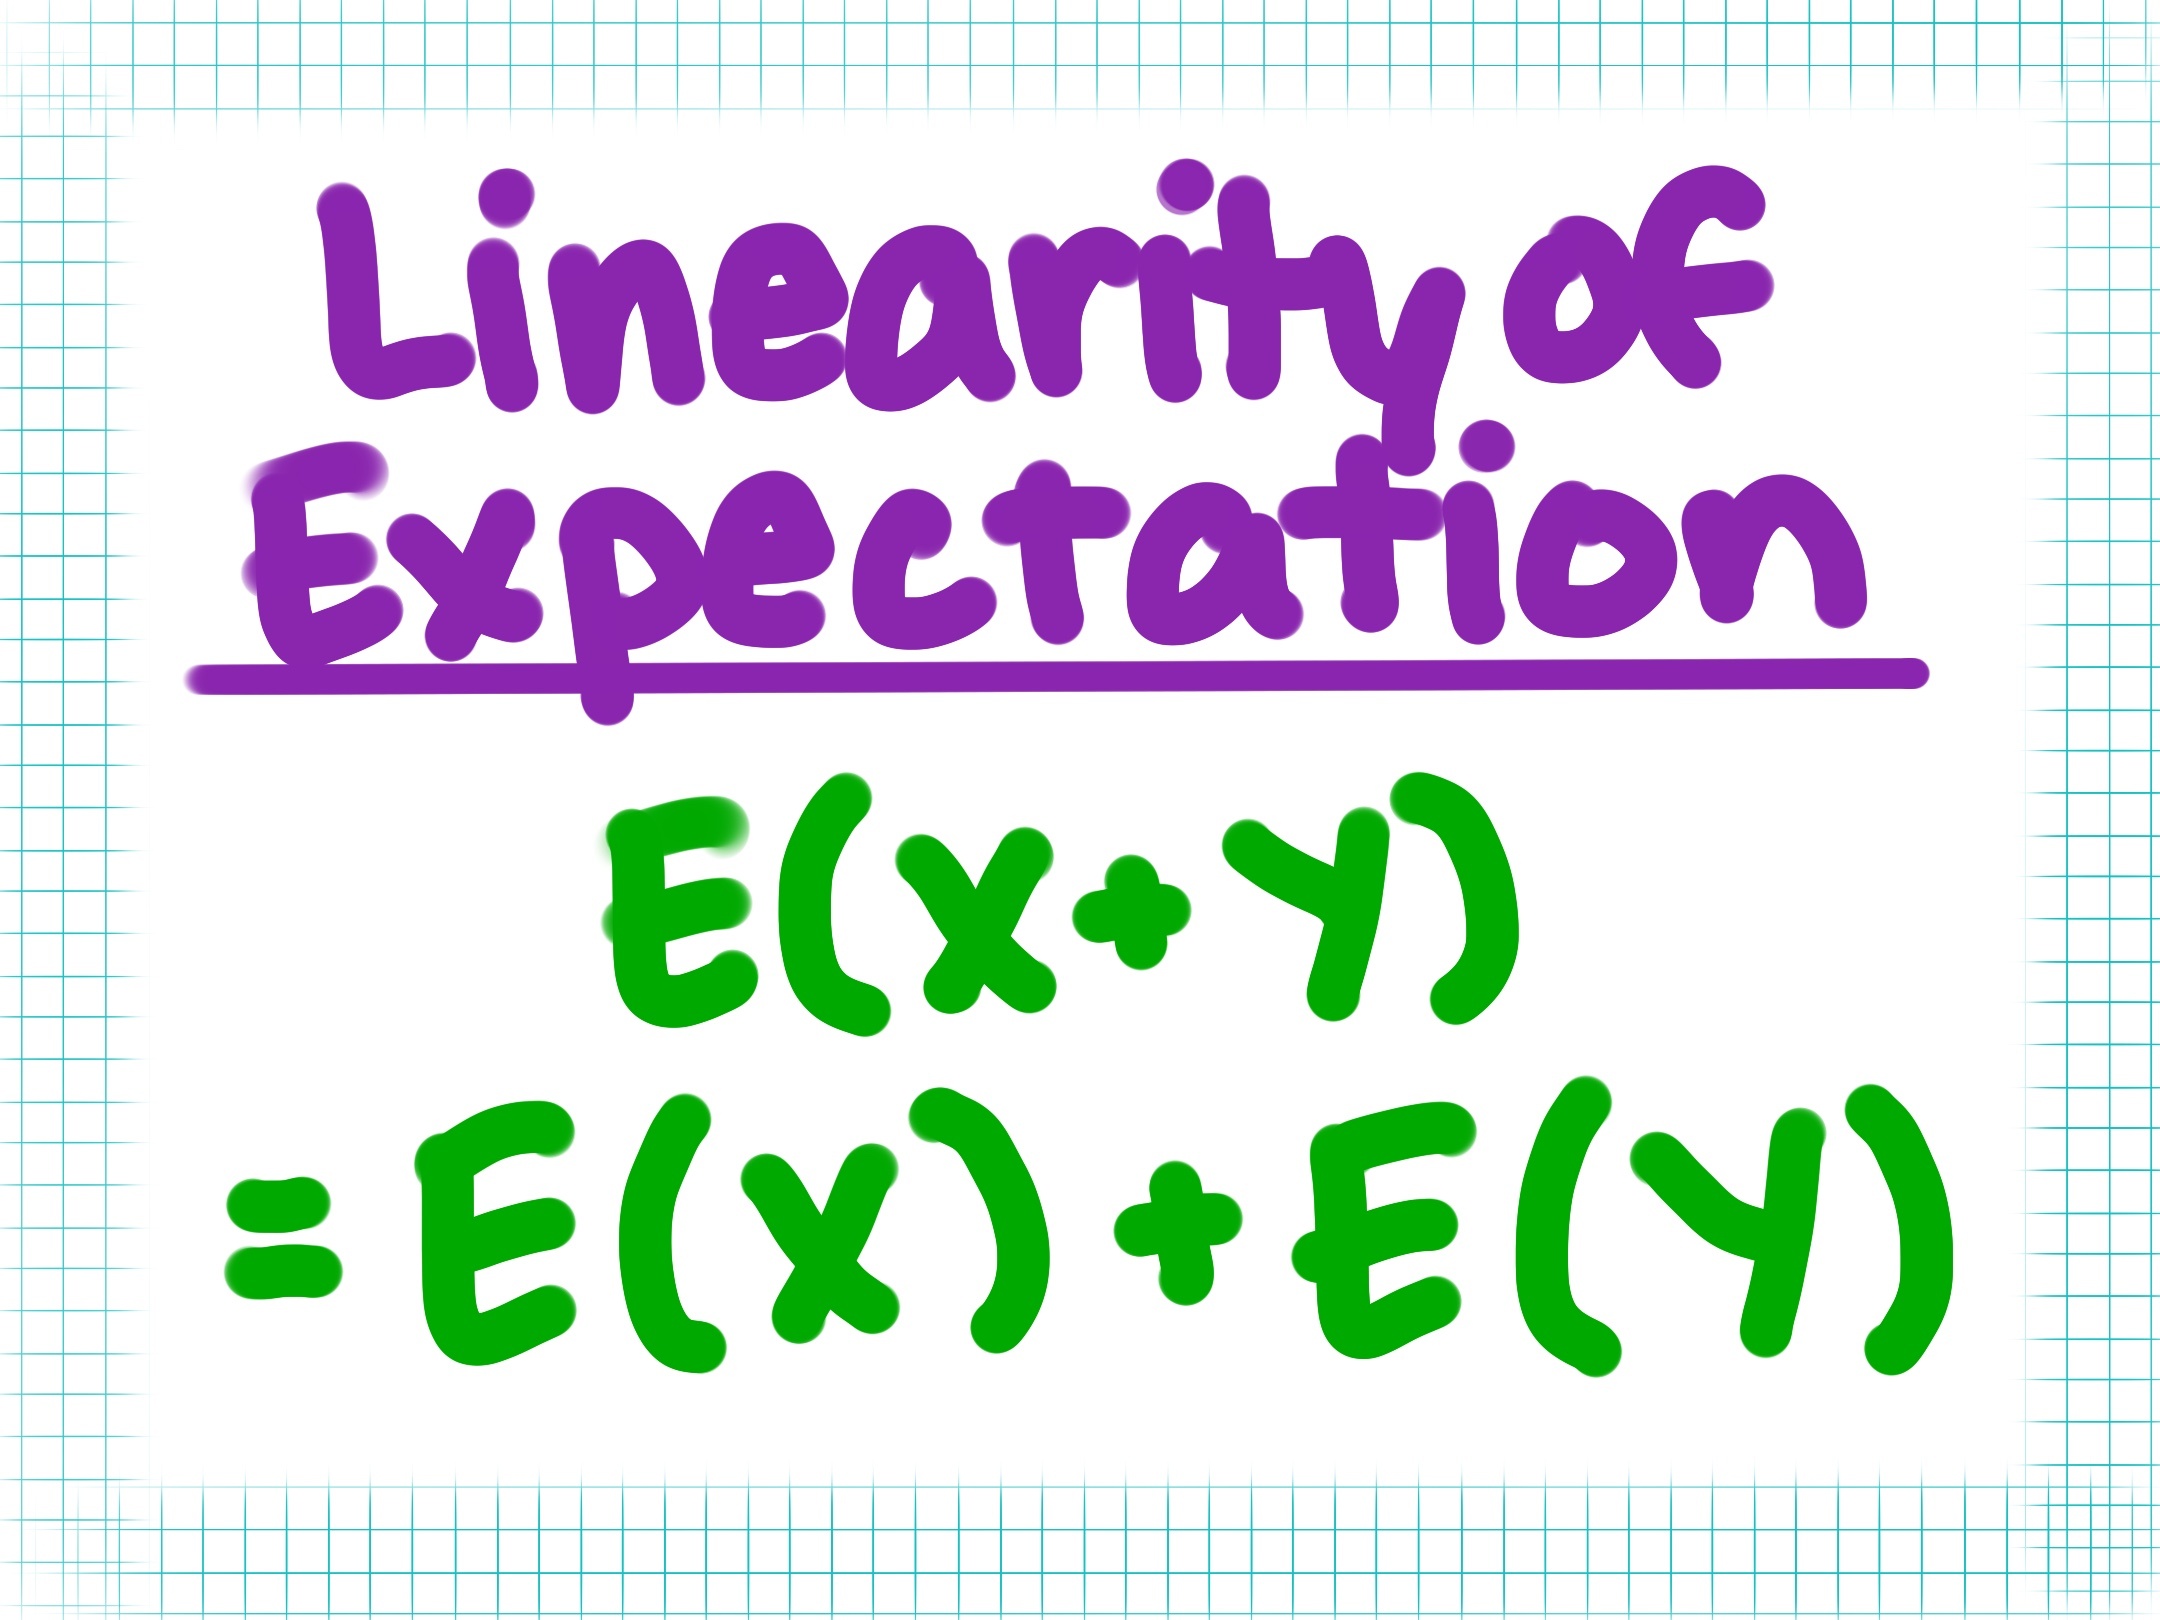Linearity of Expectation
Suppose we have random variables X and Y.
Linearity of expectation says that E[X+Y]=E[X]+E[Y].
We can prove this using definitions.
E[X+Y]=x∈Ω∑y∈Ω∑(x+y)Pr(X=x,Y=y)=x∈Ω∑y∈Ω∑xPr(X=x,Y=y)+yPr(X=x,Y=y)=x∈Ω∑xy∈Ω∑Pr(X=x,Y=y)+y∈Ω∑yx∈Ω∑Pr(X=x,Y=y)=x∈Ω∑xPr(X=x)+y∈Ω∑yPr(Y=y)=E[X]+E[Y]
This proof can be generalized to any finite number of random variables, as well as constant multipliers on the random variables.